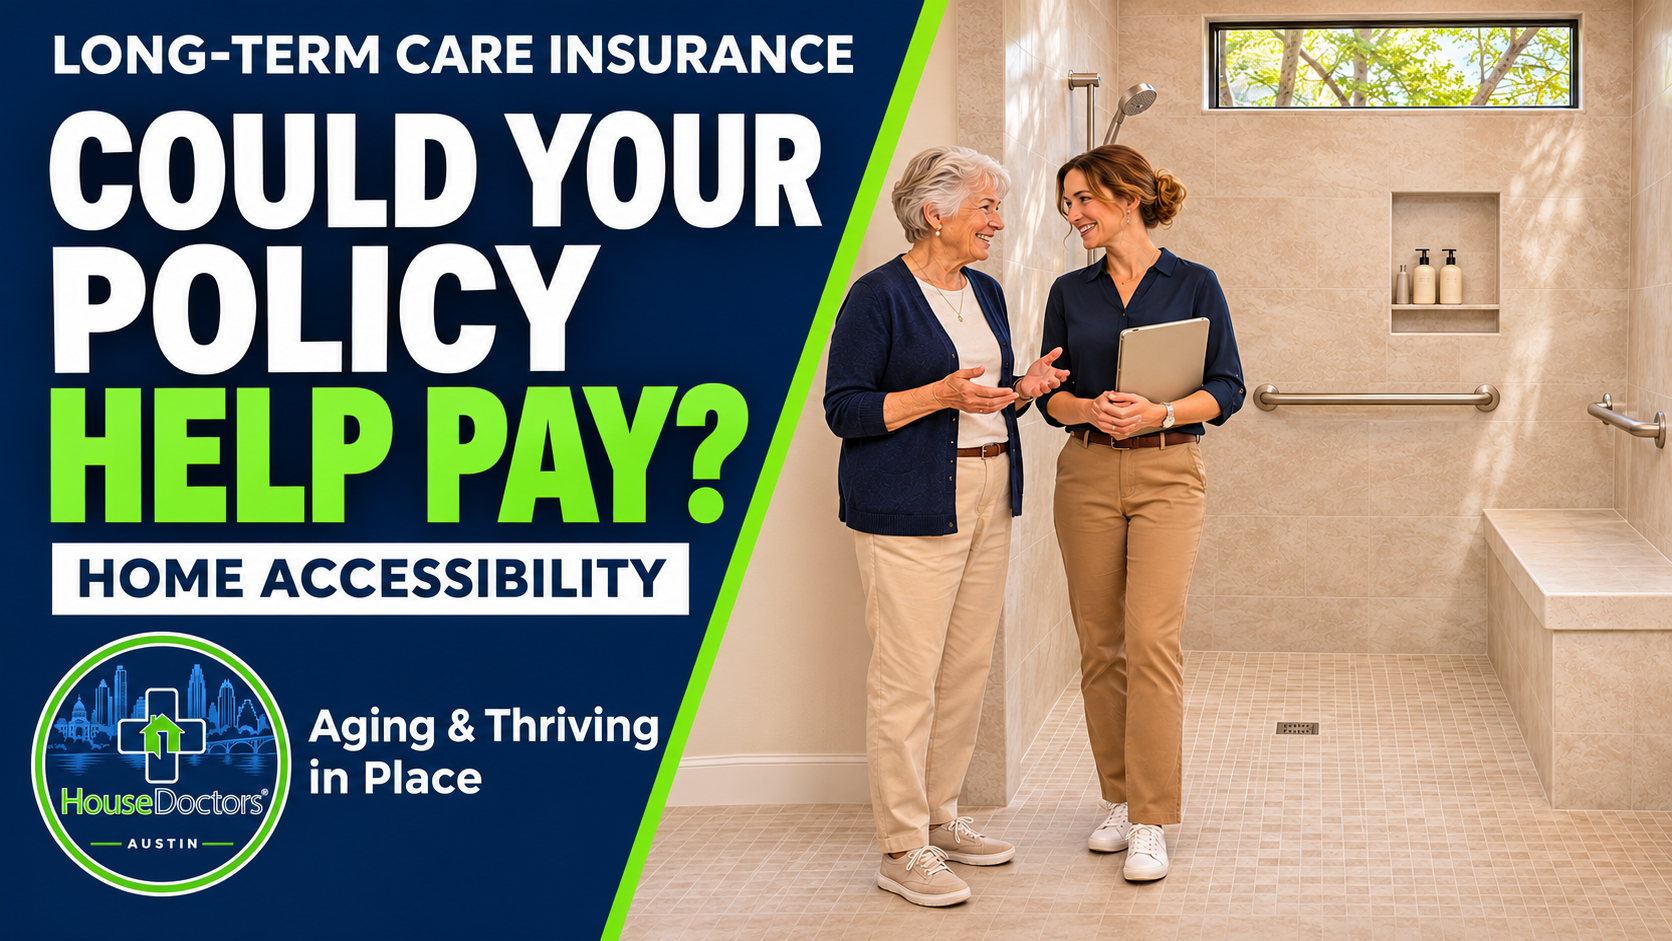
Some long-term care insurance policies may help pay for home accessibility modifications that support care at home. If you already have a policy, checking for this benefit is a useful first step before budgeting for changes. Your policy determines which projects qualify, when you can use the benefit, and how much it will pay. [1, 2]
For an Austin homeowner, staying home may mean remaining close to familiar neighbors, Sunday dinners with family, and the routines that make a place feel like your own. But a high bathtub edge, a narrow doorway, or steps at the entrance can become obstacles as mobility needs change.
At House Doctors of Austin, our Aging & Thriving in Place initiative helps families plan home improvements around those everyday needs. Understanding your insurance is one part of that planning. The goal is a home that better supports the person living in it, with a clear understanding of the costs before construction begins.
Does long term care insurance cover home modifications
It can, but coverage is policy-specific. New York Life explains that some policies provide benefits for home modifications that help people stay at home longer. The National Association of Insurance Commissioners also notes that benefit combinations vary between insurers and between policies from the same insurer. [1, 2]
Having coverage for an in-home caregiver does not, by itself, confirm coverage for construction. Look through your policy, riders, and benefit schedule for terms such as home modification, home assistance, stay-at-home benefit, or alternate plan of care. If the wording is unclear, ask your insurer’s claims department or care coordinator to identify the applicable provision.
An alternate plan of care may allow an insurer to consider services outside the standard benefit list. It is an option to ask about, not an automatic approval for a proposed renovation. [3]
An example of how a benefit can work
The Federal Long Term Care Insurance Program’s published FLTCIP 3.0 description includes a stay-at-home benefit covering eligible home modifications, such as wheelchair ramps, along with certain equipment and other supports. Its limit is 30 times the policy’s daily benefit amount, shared across the services included in that benefit. [3]
The program also explains that eligible stay-at-home expenses must be included in an approved plan of care. Although the waiting period does not apply to this benefit, the policyholder must still be eligible. This illustrates why both the benefit amount and the approval process matter. Your own policy may work differently. [4]
Accessibility improvements to discuss with your insurer
Start with the difficulty someone is experiencing in the home. A useful project addresses a specific barrier, such as getting through an entrance with a walker or reaching a bathing area with assistance. The Administration for Community Living identifies ramps, bathroom grab bars, accessible showers, handrails, improved lighting, and wider doorways as common aging-in-place modifications. [5]
The examples below are starting points for a home assessment and an insurance conversation. They are not a list of automatically covered projects.
Everyday barrier | Possible home modification |
Difficulty stepping into a tub or shower | A lower-entry or curbless shower, with suitable seating and support |
Limited support around the toilet or bathing area | Properly positioned and securely installed grab bars |
Steps between the driveway and the entrance | A ramp or a redesigned entry, where the property allows |
Difficulty moving a mobility aid between rooms | Doorway widening or adjustments to the layout |
Poor visibility or limited support along walking routes | Improved lighting and handrails |
The right solution depends on the homeowner’s abilities, equipment, available space, and care needs. An occupational therapist or another appropriate healthcare professional can help identify functional needs; a remodeler can evaluate how the recommended changes could be built.
If accessibility work is part of a larger bathroom remodel, ask the insurer to identify exactly which line items qualify. Do not assume that approval for grab bars or an accessible shower also includes decorative tile upgrades, new cabinetry, or every other part of the renovation. A clearly itemized scope helps distinguish the work submitted for coverage from the improvements you plan to fund yourself.
When you can use the benefit
Owning a long-term care policy does not necessarily make preventive remodeling reimbursable today. Policies generally have eligibility requirements, often called benefit triggers, related to needing help with activities of daily living or having a qualifying cognitive impairment. The insurer may also require clinical documentation and a plan of care. [6]
A separate elimination period is the waiting period before certain payments begin. Some benefits have different waiting-period rules, so ask specifically about home modifications instead of assuming that the rule for paid caregivers applies to construction. [4, 6]
You can review your policy and plan improvements before you need care. Just keep planning ahead separate from assuming that insurance will pay. If a safety issue needs prompt attention, discuss immediate options with your care team while coverage is being reviewed.
Questions to ask before signing a construction contract
Have your policy number and a short description of the proposed changes ready. You can start the conversation with:
“I want to understand whether my policy can help pay for changes that would make it easier to receive care at home. Can you explain the applicable benefit and what I need to submit before work begins?”
Then ask:
1. Does my policy include home modifications or another benefit that could apply to this project?
2. Do I meet its eligibility requirements, and what assessment, practitioner documentation, or plan of care is required?
3. Which work, labor, materials, and assessment costs are eligible? What is excluded?
4. Do I need written approval before signing a contract, paying a deposit, purchasing materials, or starting installation?
5. What is the available limit? Is it shared with equipment or other services, and will payment reduce my overall long-term care benefit pool?
6. Does an elimination period apply to this benefit, and do these expenses count toward that period?
7. Must the contractor meet particular requirements, and do you need multiple bids, photographs, itemized invoices, or proof of payment?
8. How and when is payment made, and what happens if the scope changes after approval?
Ask for the answers and any approval in writing. Keep the approved scope, correspondence, proposal, invoices, and payment records together. If the project changes, check whether the insurer needs to approve the revision before the additional work begins. FLTCIP specifically warns that unapproved care-plan changes can lead to reimbursement delays or denials. [4]
Payment arrangements also matter for your budget. A reimbursement policy generally pays eligible expenses after they are incurred, subject to its limits. Some policies instead provide cash benefits with different rules. Confirm which arrangement you have and what you may need to pay upfront. [7, 8]
Aging in place is about the whole home and the people in it
An insurance benefit can help with a project, but the plan should begin with how you want to live. Which entrance do you use every day? Can you reach the bedroom and bathroom comfortably? Is there room for a caregiver to assist? Would a focused improvement solve the problem, or does the layout need more substantial work?
These questions guide our Aging & Thriving in Place initiative. House Doctors of Austin stands for family and community: helping create spaces that bring people together and helping families remain in the homes where they have made memories, near the communities they know.
Our team’s Age Safe® America Senior Home Safety Specialist® (SHSS) certification complements our remodeling experience. We help homeowners explore home safety improvements and accessibility renovations, from grab bar installation to bathroom remodeling and changes to the way a space functions. Our construction assessment serves a different purpose from the clinical evaluation or insurance review your policy may require.
Our process begins with an in-person walkthrough to understand your goals and assess the space. We then prepare a formal written proposal through our operations manager, Tammy Robinson. If you intend to seek insurance reimbursement, let us know during planning so we can discuss the construction information your insurer requests. Your insurer determines coverage and claim approval.
Frequently asked questions
Will long term care insurance pay for a complete bathroom remodel
Not automatically. A policy may help pay for specific approved accessibility modifications without paying for the entire renovation. Ask the insurer to review an itemized proposal and confirm the covered amount before you commit to the project.
Can I install grab bars first and claim reimbursement later
Check first if you intend to rely on reimbursement. Your policy may require advance approval, an approved care plan, or specific documentation. Completing the work before confirming those requirements can put reimbursement at risk. [4]
Can I plan accessibility changes before I qualify for benefits
Yes. Planning ahead can help you decide which improvements to make now and which to incorporate into a future remodel. However, a useful preventive improvement is not necessarily an eligible insurance expense. Ask your insurer about the rules for your particular benefit. [6]
Is a home safety assessment the same as insurance approval
No. A home safety assessment helps identify barriers and potential improvements. The insurer separately reviews eligibility, covered services, and payment requirements. House Doctors of Austin can evaluate construction needs and provide a proposal; we cannot guarantee insurance payment.
Plan a more accessible home in Austin
If you or a parent wants to remain at home as care needs change, begin with two conversations: one with your insurer about the benefits available under your policy, and one about how the home can better support daily life.
House Doctors of Austin provides remodeling and accessibility improvements for homeowners in Austin and surrounding communities, including Cedar Park, Round Rock, Pflugerville, and Georgetown. Contact Tammy and the team to arrange an in-person walkthrough and discuss your aging-in-place goals.
Call (737) 371-8827 or request a consultation online.
This article provides general education. Policy terms, eligibility, limits, and insurer approval determine coverage. Confirm your benefits directly with your insurer or a licensed insurance professional.
Sources and further reading
Sources checked November 4, 2026. Insurer examples illustrate particular benefits and do not establish coverage under another policy.
1. New York Life — Long-term care insurance offers more than just nursing home coverage
2. National Association of Insurance Commissioners — Long-Term Care Insurance
3. Federal Long Term Care Insurance Program — Program Details for FLTCIP 3.0
4. Federal Long Term Care Insurance Program — Using Your Benefits
5. Administration for Community Living — Staying in Your Home
6. Texas Department of Insurance — Long-term care insurance guide
7. John Hancock — Benefit reimbursement
8. Administration for Community Living — Receiving Long-Term Care Insurance Benefits